Bitcoin DeFi Firm Liquidium Explains How ICP Integration Smooths Lending Experience
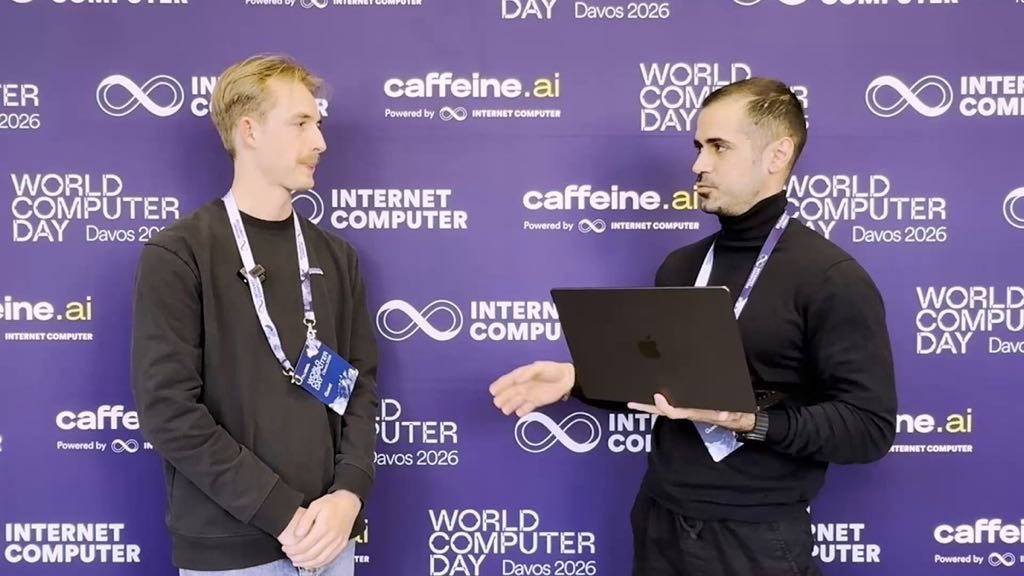
Liquidium’s chief executive, Robin Obermaier, discussed how the company uses technology from the Internet Computer Protocol (ICP) to simplify and secure its Bitcoin‑based lending services, offering an unusual example of real‑world adoption of cross‑chain infrastructure.
At the World Computer Summit in Davos, Obermaier pointed to one of the practical advantages of integrating ICP’s Chain Fusion tools: it lets the protocol co‑ordinate actions between different blockchains without the usual reliance on custodial bridges, which have been criticised in the past for security gaps. “Bitcoin was built for self‑sovereignty, not surrendering keys to centralised bridges,” he said, emphasising user control and security in the process.
Liquidium operates a peer‑to‑peer lending platform where users can borrow Bitcoin against assets such as Ordinals, Runes and BRC‑20 tokens, and lenders can earn yield by providing Bitcoin collateral. By using ICP’s backend signing and messaging layer, the system can automate key steps like issuing loans and managing repayments while keeping all transactions native to the chains involved, without wrapping or moving assets off their original networks.
The figures involved illustrate the scale at which this model has gained traction. Liquidium’s protocols have passed more than $500 million in cumulative lending volume, with tens of thousands of individual loans recorded on the Bitcoin network.
Obermaier acknowledged that decentralised finance built around Bitcoin is still emerging. “DeFi on Bitcoin is still in its infancy,” he acknowledged in a previous discussion, while stressing the opportunities for cross‑chain services that retain Bitcoin’s native security.
This approach contrasts with some existing DeFi products that route assets through intermediary networks or custodians to achieve cross‑chain functionality. By keeping collateral and loan mechanics on native networks, Liquidium and similar projects aim to offer seamless lending functions without adding operational complexity for users.
Critics and cautious observers note that the broader market and regulatory context for decentralised lending remains unsettled, and innovations like ICP integration carry their own technical and governance questions. However, for developers and participants who embrace native‑chain models, the practical outcomes of such integrations are becoming clearer as products move from concept to daily use.